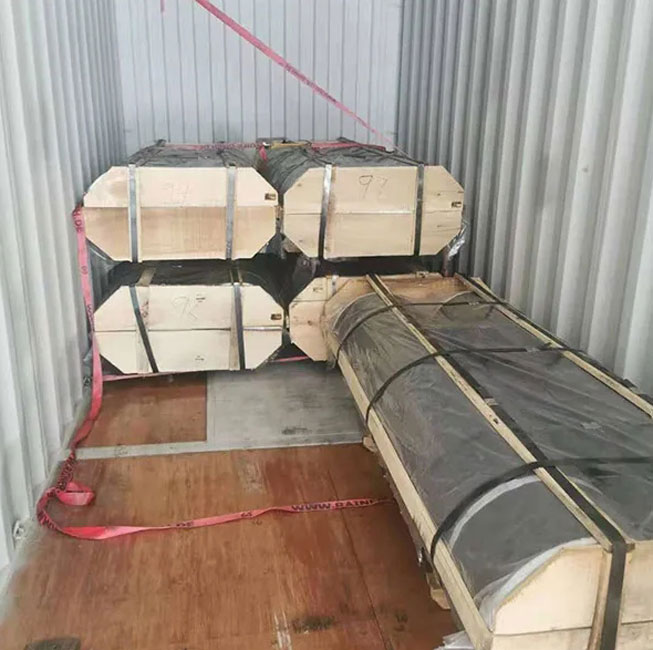
Graphite Electrode market players rely on product innovation, capacity expansion, and strategic partnerships to maintain their competitive stance. However, the industry remains susceptible to supply chain disruptions that can impact the availability and cost of raw materials.
Moreover, growing sustainability trends are prompting industry sectors to seek carbon reduction goals. This shift creates opportunities for UHP graphite electrode manufacturers to align their products with battery manufacturing, enhancing value propositions and competitive landscapes.
The graphite electrode market continues to innovate, with a focus on improving performance and environmental impact. Manufacturers are also working to reduce operational expenses by leveraging energy efficiency solutions. These advances can improve profitability and boost operational lifespans.
The market faces several restraining factors, including price volatility in raw materials such as needle coke and coal tar pitch. These products account for a large percentage of production costs. Any price increase for these raw materials will lower the profitability of producers.
To mitigate these challenges, companies are investing in technology to increase capacity and production efficiencies. For instance, Jilin Carbon Limited partnered with an electric vehicle battery manufacturer to produce high-quality UHP graphite for the EV industry. This move reflects the fusion of industries and the need for producers to align with sustainability trends. In addition, they need to diversify into new markets. This will help offset domestic demand pressures. Moreover, it will reduce dependency on imported needle coke.
Steel production through EAFs is a major demand driver in the graphite electrode market. This steelmaking process is favored for its environmental benefits, energy efficiency, and flexibility. Its use is increasing as countries develop their infrastructure and industrialization. This growth in demand drives the need for new EAF facilities, boosting graphite electrode consumption.
EAF steelmaking requires large amounts of UHP and hydraulic electrodes to melt scrap rapidly. This type of steelmaking accounted for over 70% of global electrode usage in 2024, reflecting its high demand. In addition, EAFs can be activated and deactivated quickly, reducing idle time and energy consumption.
Governments and private companies are investing in EAF facilities to boost local capacity and reduce dependence on imported raw materials. For example, China has backed several projects to increase UHP electrode production and decrease its dependence on needle coke imports. Additionally, manufacturers are enhancing their product offerings to meet customer demands. For example, Tokai Carbon developed an IoT-integrated graphite electrode for real-time performance monitoring.
Needle coke is the key raw material for graphite electrode production. The market’s volatility is closely linked to the steel industry’s health, as EAF-based steelmaking offers a more environmentally conscious approach compared to basic oxygen furnace (BOF). Consequently, the demand for needle coke increases.
GrafTech International Ltd and Showa Denko (Resonac) are among the leading players in the market, as both companies operate integrated manufacturing with needle coke and electrode production facilities. Their vertically integrated models enable cost control and long-term supply contracts with steel producers.
The high price of needle coke has been a challenge for the graphite electrode market, as manufacturers seek to maximize business margins. Despite this, investors are bullish on the prospects of the sector, with sustainable and carbon neutrality targets driving industrial policies worldwide. In addition, technological breakthroughs in the UHP electrode manufacturing process are boosting energy efficiency and durability, which lowers operational costs. This boosts the market’s growth potential.
A recent technological advance is amplifying graphite electrode manufacturing methods, improving battery efficiency and lowering cost. The new process creates more precise graphite layers and improves electrode adhesion, allowing for increased current capacity without altering the battery’s structure. This development can boost lithium-ion battery production and increase the lifespan of batteries by reducing cell resistance and discharging times.
Currently, UHP graphite electrodes lead the market due to their high performance and superior temperature-handling capability. They are widely used in the EAF steelmaking sector, which accounts for a majority of global demand. Other industrial applications for these electrodes include thermal and electrical power generation, oil drilling, and aerospace technology.
The report segmentes the graphite electrode rod market into North America, Europe, Asia-Pacific, and Middle East & Africa, detailing demand drivers, investment flows, import-export balances, and regional policy frameworks. It also profiles key vendors based on their product portfolios, capacity expansion, and strategic initiatives. Companies are investing in R&D to develop new products that address emerging trends and industry demands.
 English
Write a Message